VIPs
- The October Construction spending report fell 0.8% and September’s was revised lower resulting in back-to-back declines of more than 1%, a regular feature of the last recession; the breadth of decline was widespread with only two of 14 sub-categories above their Q3 average
- The nonresidential construction weakness in this quarter’s first month suggests a third consecutive double-digit decline; even with the Fed growing its balance sheet, it’s clear the private construction cycle has peaked and is at best plateauing
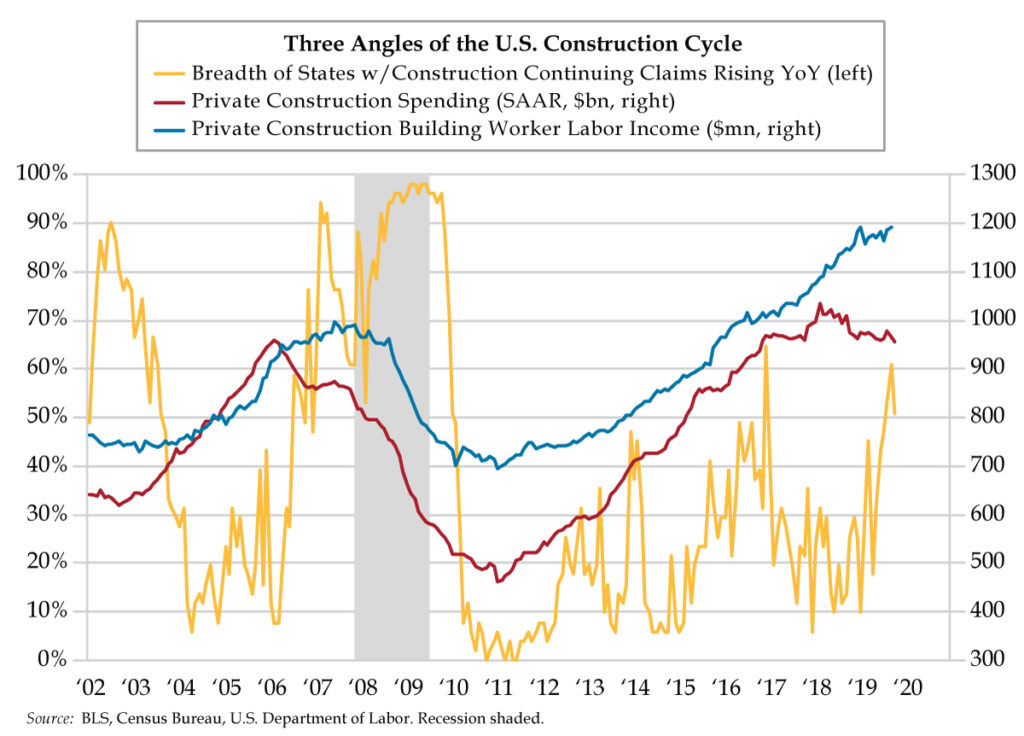
- Peak construction spending should herald peak earnings; for the last three months, the breadth of states with construction continuing jobless claims rising YoY breached 50% while total U.S. construction continuing claims are higher than last year’s for five straight months
On August 20, 1920, a meeting held at the Jordan and Hupmobile auto showroom in Canton, Ohio, formed the American Professional Football Conference. Two years later, it was renamed the National Football League (NFL). This year, the NFL celebrates its 100th season. To honor its past, the NFL 100 All-Time Team is being unveiled throughout the season. It’s a shame there’s no room on that list for second string quarterbacks. Football historians remember Frank Reich’s 1993 Comeback, when he brought the Buffalo Bills back to win after trailing the Houston Oilers 35-3. Others reminisce about Don Strock’s 1982 Epic in Miami. Down 24-0 after the first quarter, Strock came off the Miami Dolphins bench to spark a rally against the San Diego Chargers and force overtime in one of the greatest games in NFL history.
True cycle chasers get teary-eyed each month when the perennial second stringer of the U.S. economic calendar hits the newswires. The first business day of the month is marked by the release of the bellwether Institute for Supply Management (ISM) Manufacturing Report on Business. At the same 10:00 a.m. EST release, the Census Bureau publishes the Construction Spending report. Month in and month out, it plays second fiddle to the timely and breathlessly followed ISM report.
But the October construction figures didn’t fly under our radar. In fact, the 0.8% drop that disappointed every estimate in the Bloomberg survey combined with an additional -0.8% downward revision to September, lowering it to a -0.3% decline from a 0.5% advance. The headline number includes both public and private construction. The significant shift of momentum was most prevalent in the back-to-back declines of more than 1% for the private sector, something we haven’t seen since 2011 and a regular feature in the 2007-09 recession.
In October, private sector weakness was widespread across both residential and nonresidential construction. Of the 14 sub-categories in private construction, 12 came in below their respective third-quarter averages. The only two groups in the black were new single-family residential construction and new religious building construction – houses and houses of worship. OMG!
Breadth this bad occurred only once in the early 2000s expansion, in 2002’s third quarter, then again in the Great Recession in 2009’s first quarter and twice in the recovery that followed in the third quarter of 2009 and 2011’s first quarter.
The Construction Spending report includes key source data for residential and nonresidential investment GDP inputs. The weakness in the current quarter’s first month is more pronounced in nonresidential, so much so that real business investment in structures is poised to register its third consecutive double-digit decline, matching the streak seen in the 2015-16 industrial recession.
The difference between then and now? Back then, the collapse in oil and gas investment, that is, the plunging rig count, was at the heart of the downturn. This time, it is broad-based declines across many property types.
We illustrated private construction in today’s graphic in level terms (red line above) to make a point. It’s clear that the private construction cycle has peaked. Given the $324 billion in time (and counting) the Federal Reserve has bought with Powell’s Printing Press, one could venture a best-case scenario of the cycle simply plateauing.
Will the Fed’s three rate cuts and growing its balance sheet make lenders more eager to extend credit? Will developers be lured back into a developing frame of mind? Past Feathers have noted the multi-year tightening in lending standards for commercial real estate loans and lower demand for these products to fund new buildings. Revitalizing demand might require more convincing in this long lead time sector.
It is especially the case in commercial construction that the topping process is drawn out due to the length of time it takes to complete large projects. Furthermore, peak construction spending eventually morphs into peak earnings for construction workers (blue line above). A double-top in January and September 2019 is tentatively forming for labor income. This Friday’s jobs report will update the aggregate weekly paycheck picture.
Stepping back, it’s one thing to be past peak; it’s another to be end-of-cycle, which has yet to be determined. We can get close to real-time via weekly continuing jobless claims data, as in the number of workers collecting unemployment insurance.
On that count, the breadth of states with continuing claims rising year-over-year in the construction sector has crested 50% in August, September and October (yellow line above). Moreover, total U.S. construction continuing claims have been above year-ago levels for the last five months. We last saw this persistence manifest in the pre-recession months of early-2007.
One last thing. These aren’t second-string states. Weakness is prevalent in high-population states like Texas, New York, Florida, Illinois, Pennsylvania, Ohio, North Carolina, Massachusetts and Washington.