Ask younger generations whom they would associate with the voice of God, and the most popular response might be Morgan Freeman for his portrayals in 2003’s Bruce Almighty and 2007’s Evan Almighty. American football fans who grew up in the 1960s and 1970s would answer differently. Widely known as the “Voice of God” by NFL Films’ fans because of his resonant style, “John Facenda could read a laundry list and make it sound like the Constitution of the United States,” said Steve Sabol, co-founder of NFL Films. His numerous memorable narrations cover a span from 1967’s They Call It Pro Football to 1974’s The Autumn Wind. The poetry of his deliberate baritone delivery was unmatched, especially from this passage: “The fourth quarter. Time is no longer a referee, but an executioner. The shadow of the stadium stretches across the field, a reminder that the sun is setting on someone’s hopes. This is when the long afternoons of summer training pay their final dividends. This is the hour of the veteran. The rookie has played his game; now, it is time for the men.”
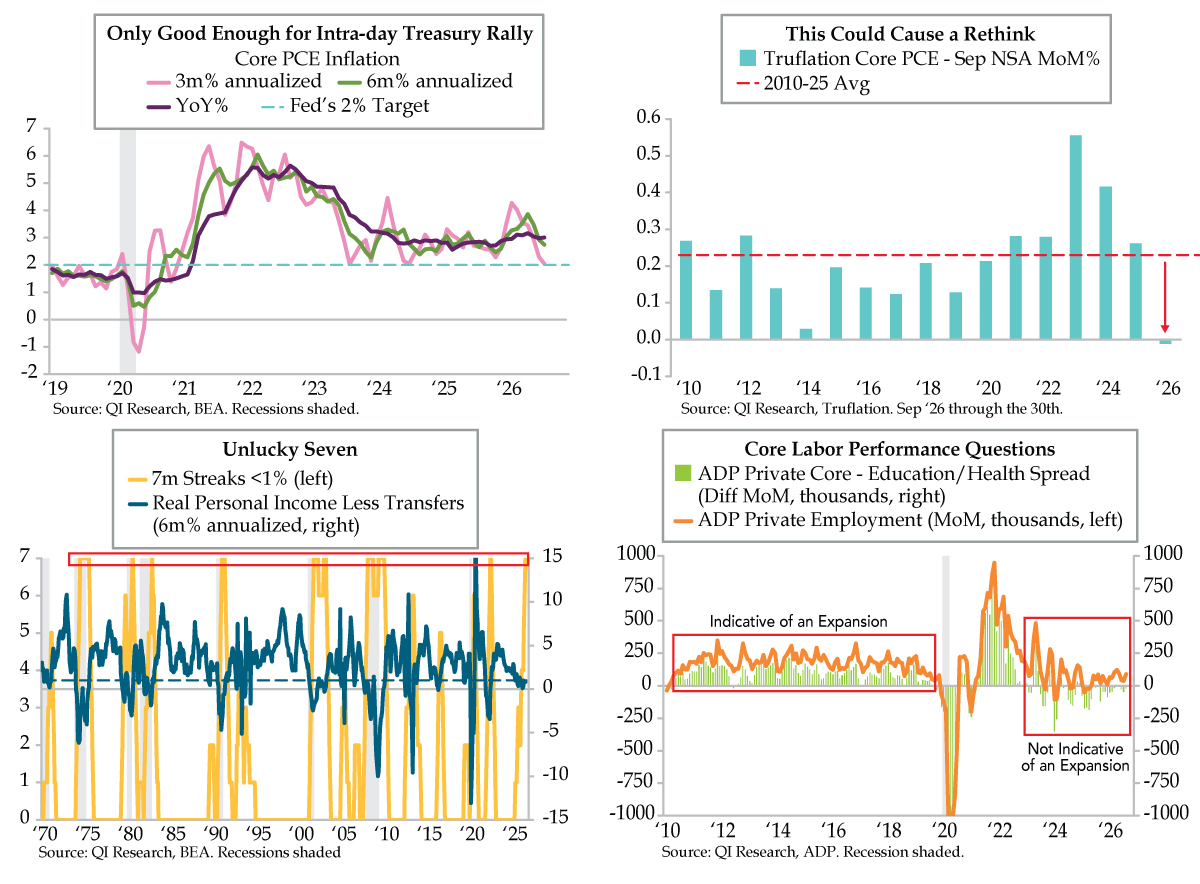
Today’s start of the fourth quarter comes on the heels of relief on the inflation front, at least for day traders. August’s core PCE price index rose 0.247% month-over-month (MoM), rounding down to 0.2% vis-à-vis the 0.3% consensus expectation. Also unrounded to three decimal points, 12 of the 14 prior months through July were revised downwardly. Yields on the 2-year and 10-year rallied to as low as 4.82% and 5.20%, respectively, before boomeranging to close higher on the day. The core’s three-month annualized rate fell to 2.05%, the lowest since July 2024’s 2.04% (lilac line). Farther back, August 2023’s 2.03% level helps draw the Fed’s 2% target more like a support line for the short-run core inflation trend. A move through this support to a 1-handle could have created more traction for a long-lived Treasury rally. The smoother six-month and year-over-year (YoY) trends did not make the same progress as the three-month metric — the former eased mildly to 2.74% from 2.93% (green line) and the latter ran in place at 3.01% from 2.98% (purple line).
Truflation’s August core PCE projection of 0.19% MoM landed on the correct side of the consensus, as noted in Wednesday’s Feather. With the fourth quarter upon us and Truflation’s September core calculations just completed, we can see a major difference relative to past Septembers. This year’s -.012% not seasonally adjusted (NSA) MoM drop is a prominent outlier. Since its 2010 inception, Truflation’s core PCE has never posted a September sequential decline. Compared to the .229 average of the prior 16 years, the .241 MoM shortfall relative to trend could lead to a notable downside surprise once September core PCE is released on October 29th. After the National Accounts’ revisions, Truflation’s average .04 MoM percentage point difference from February to August suggests the next core PCE figure could come in at a (rounded) 0.1% MoM pace or lower.
Cumulative inflation has clearly taken its toll — consumer spending’s fundamental fuel registered the second MoM compression in the last five months. The National Bureau of Economic Research’s coincident cycle indicator, real personal income less transfers (PILT), has transitioned from an unbroken expansion stretch in the 27 months ended January 2025 to uneven performance since. The smoothed six-month annualized rate to benchmark business cycles has run under the 1% threshold for seven straight months through August 2026. While the path treads water, the seven-month string raises caution flags. In economic cycles, the ‘7’-month mark first occurred in July 1974, August 1980, December 1982, February 1991, November 2001 and March 2008, all of which overlapped with recessions. July 2022’s observation landed right in the middle of the post-COVID inflation acceleration. Given September’s energy price surge, inflation-adjusted variables face downward pressure, making a continuation of real PILT’s sub-1% six-month trend a near certainty.
Even more noteworthy, nominal personal income’s largest influence from the benchmark revision came from personal interest income. Personal income was amended upward by $446 billion over the five years ended July 2026. July’s interest income revision, up $461 billion, accounted for more than the entirety of the aggregate adjustment. Other upward moves for personal income components came from employee compensation ($130.7 billion) and rental income ($42.6 billion). For completeness, downward offsets came from personal dividend income (-$105.2 billion), transfer payments (-$57.9 billion) and proprietors’ income (-$39.3 billion).
Interest income is not the backbone of American consumers’ budgets; it doesn’t fund their standards of living. That comes from wages and salaries, underpinned by the labor market. A check-in with ADP’s private payrolls revealed a pick-up in private job growth to September’s 90,000 pace (orange line). The three-month high revealed more than half (55,000) was generated by “recession-proof” education and health services. The goods-producing sector continued to outperform the service side (ex-education and health). Construction (15,000; thank you, data centers) and manufacturing (17,000; supply chain capacity pressures) collectively outpaced financial employment (-16,000) and professional and business services (-11,000). Leisure and hospitality also added jobs (22,000), but we wouldn’t hold our breath on sustained gains with future downside travel risks surfacing as detailed in Wednesday’s Feather.
Under the surface of ADP’s top line is a relative spread between the Private Core and the education and health industry. A vigorous economic expansion is characterized by the former’s job creation outpacing the latter; this was supremely evident in the 2010s expansion (green bars). Over the last three years, the inverted spread is indicative of the opposite and questions the ongoing subdued picture for real PILT. The building blocks of the consumer spending outlook are being driven by traditionally non-cyclical sectors. Time is no longer a referee with the upside down-ness of the private labor market at the fourth-quarter’s outset and long-term interest rates moving up and to the right.