Tongue twisters aren’t just for fun. As far back as the 18th century, they were used as a teaching tool. Educators, speech tutors and elocutionists began codifying tongue twisters into formal usage; they were used in schools to teach children clear articulation, proper diction and precise pronunciation of difficult letter combinations. The first published children’s elocution book was Peter Piper’s Practical Principles of Plain and Perfect Pronunciation. Credit the Internet Archive for this twister from the book’s “P-P-P-Preface” that takes the original Peter Piper to another level: “Peter Piper, without Pretension to Precocity or Profoundness, Puts Pen to Paper to Produce these Puzzling Pages, Purposely to Please the Palates of Pretty Prattling Playfellows, Proudly Presuming that with Proper Penetration it will Probably, and Perhaps Positively, Prove a Peculiarly Pleasant and Profitable Path to Proper, Plain and Precise Pronunciation. He Prays Parents to Purchase this Playful Performance, Partly to Pay him for his Patience and Pains; Partly to Provide for the Printers and Publishers, but Principally to Prevent the Pernicious Prevalence of Perverse Pronunciation.”
The pervasive “low hire, low fire” narrative qualifies as a greatly abbreviated tongue twister to this mic drop of mic drops (say it five times fast and you’ll hear what we mean). Refocusing, Thursday’s early U.S. economic data from Challenger, Gray & Christmas and the U.S. Department of Labor reiterated the relevance of the repetitive remark from the reports’ raw results. Challenger hiring plans perfectly and plainly proclaimed:
“Employers announced plans to hire 90,787 workers in September, up from the 12,325 plans announced in August, as seasonal hiring announcements have begun. However, it is down 23% from the 117,313 announced in September 2025, and the lowest September total since 2011, when 76,551 hiring plans were recorded. Announced seasonal hiring is muted so far this year.”
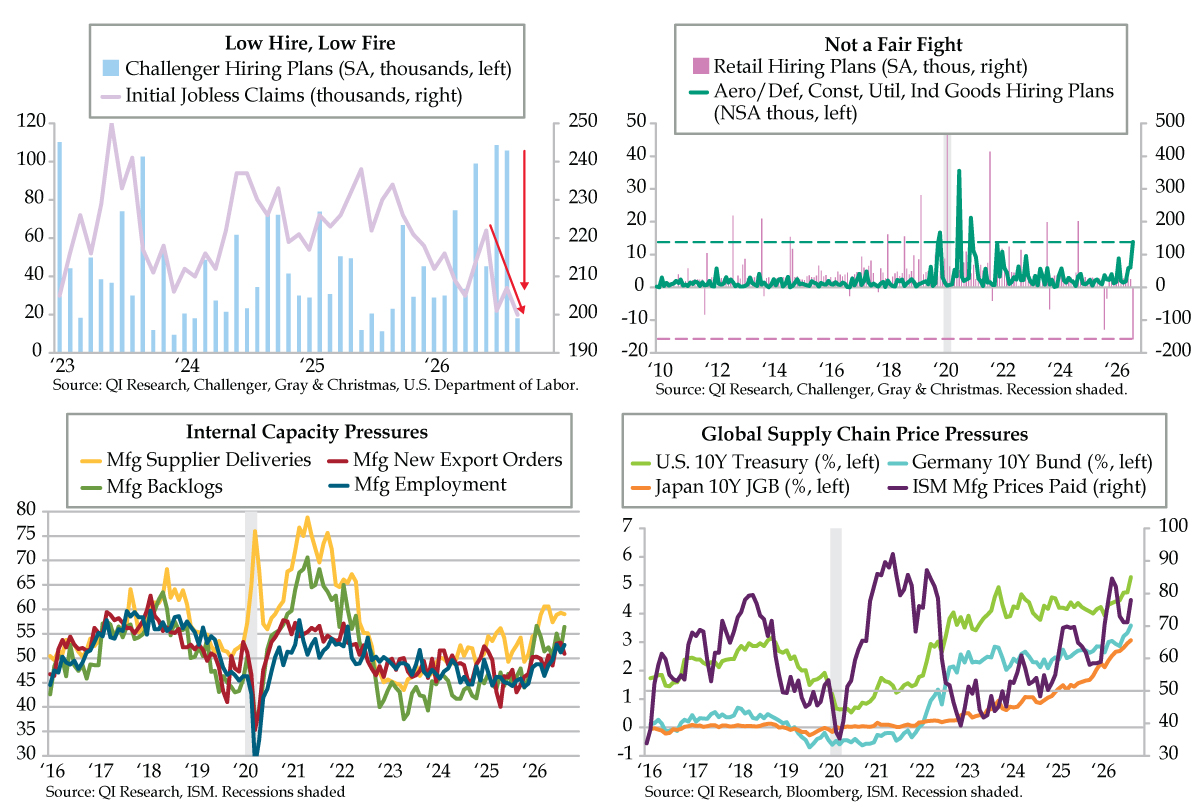
End-of-year seasonal hiring patterns make for a rather lumpy picture. Applying a seasonal adjustment shows the sequencing of the last few months has taken a turn for the worse. Seasonally adjusted hiring plans fell sharply, to 18,000 from July’s 109,000 and August’s 106,000 (light blue bars). September’s showing was the lowest since August 2025’s 11,000.
“Low fire” couldn’t have been more obvious from the initial jobless claims headline. The 197,000 print didn’t just come in below the 200,000 consensus estimate, it was the third straight week under the 200,000 mark. The last time a streak of these lows occurred was in the three weeks ended October 4, 1969, as in 2,973 weeks ago.
When it comes to end-of-year hiring plans, there’s the retail sector and then there’s everybody else. As Challenger outlined, “Spirit Halloween and Michaels are the only Retailers who have announced hiring plans this year, a combined 62,000 seasonal hires. This is compared with seasonal employers announcing a combined 100,800 last September.” To best judge the direction of influence on retail payrolls, apply a seasonal adjustment. The results are striking. September’s -159,000 literally falls off the bottom of the chart (lilac bars). Last September’s seasonal hiring was also below normal; still, the -129,000 stands in stark contrast to the normal positive cadence.
No doubt, there were winners in the entrails of Challenger’s hiring plans. Four industries posted big numbers relative to their past trends: Aerospace/Defense 5,300, Utilities 4,200, Industrial Goods 3,108, and Construction 1,256. These figures landed 216%, 1,276%, 158% and 417%, respectively, above their prior 12-month averages. Altogether, the 13,864 total was a serious departure from the norm (teal line). The need for additional labor resources reflects the outlier vibes generated from defense, data centers and manufacturing capacity pressures.
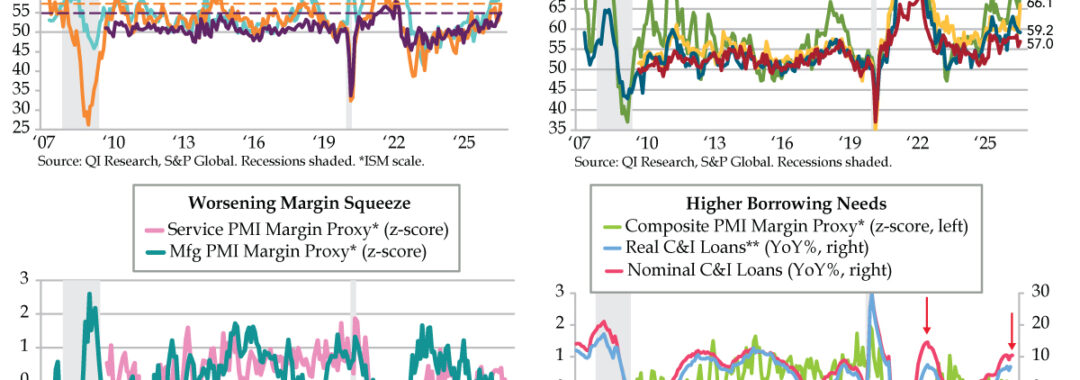
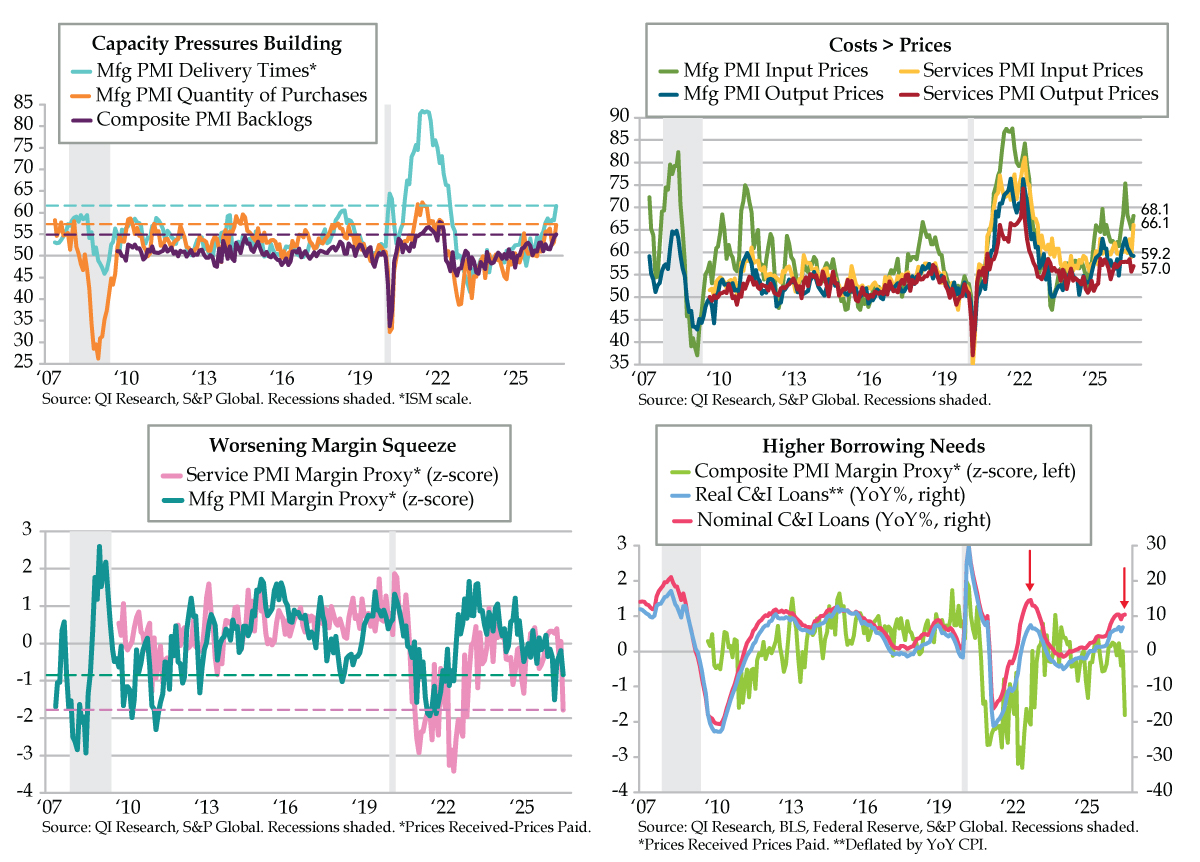
The September ISM manufacturing report piled on evidence to the capacity pressure narrative. Starting with Backlogs, the current 56.4 was just the second, alongside February’s 56.6, above the 55 threshold over the last four years (green line). Supplier Deliveries, staying elevated at 59.0, sustained bottleneck risk through the conduit of longer lead times (yellow line). A comment from the machinery industry was telling: “Orders have doubled yet again, and delivery times have also doubled, in the semiconductor, electronics and government sectors, with remaining sectors flat to down. Coupled with supply chain lead times and pricing pressures, the factory backlog has nearly doubled.”
Widening Backlogs underpinned Employment’s increase to 52.7, nearly identical to July’s four-year high of 52.8 (dark blue line). ISM’s rule of thumb relative to manufacturing payrolls equates the 50.3 level to a breakeven, suggesting the 10,000-consensus estimate for today’s employment report leans in the right direction. Alternatively, a read-through to ISM orders metrics supports the notion that capacity pressures are more an internal than an external story. Headline New Orders rose to 55.3, while New Export Orders fell to 50.9 and underperformed New Orders in 23 of the past 25 months.
Price pressures, as manifest in ISM Prices Paid, broadcast the ongoing inflationary narrative across financial markets. The 77.9 beat of the 73.0 market’s expectation kept this litmus test of the global industrial supply chain at heightened heights. The eight consecutive readings above the lofty 70-level mark a rare event — over the last 30 years, a streak of this duration only has occurred 12 other times.
With that as backdrop, long-term bond yields are behaving like common moving average lines that default in Bloomberg charts. In the last five years of the 2010s, the U.S. 10-year Treasury drew a smoother path to ISM Prices (lime line). Today, the uptick through the 5% yield has tracked sympathetically with upstream cost pressures. It’s no coincidence that Germany’s 10-year Bund (aqua line) has moved, tracking ISM Prices higher for nearly two years. And Japan’s 10-year JGB looks like a technical support line for the “higher lows” dating as far back as 2023. As one of the first national price gauges each month, ISM Prices sets a tone. Right or wrong on the fundamentals, the latest installment sides with bond bears. Tongue twisters, not necessary.